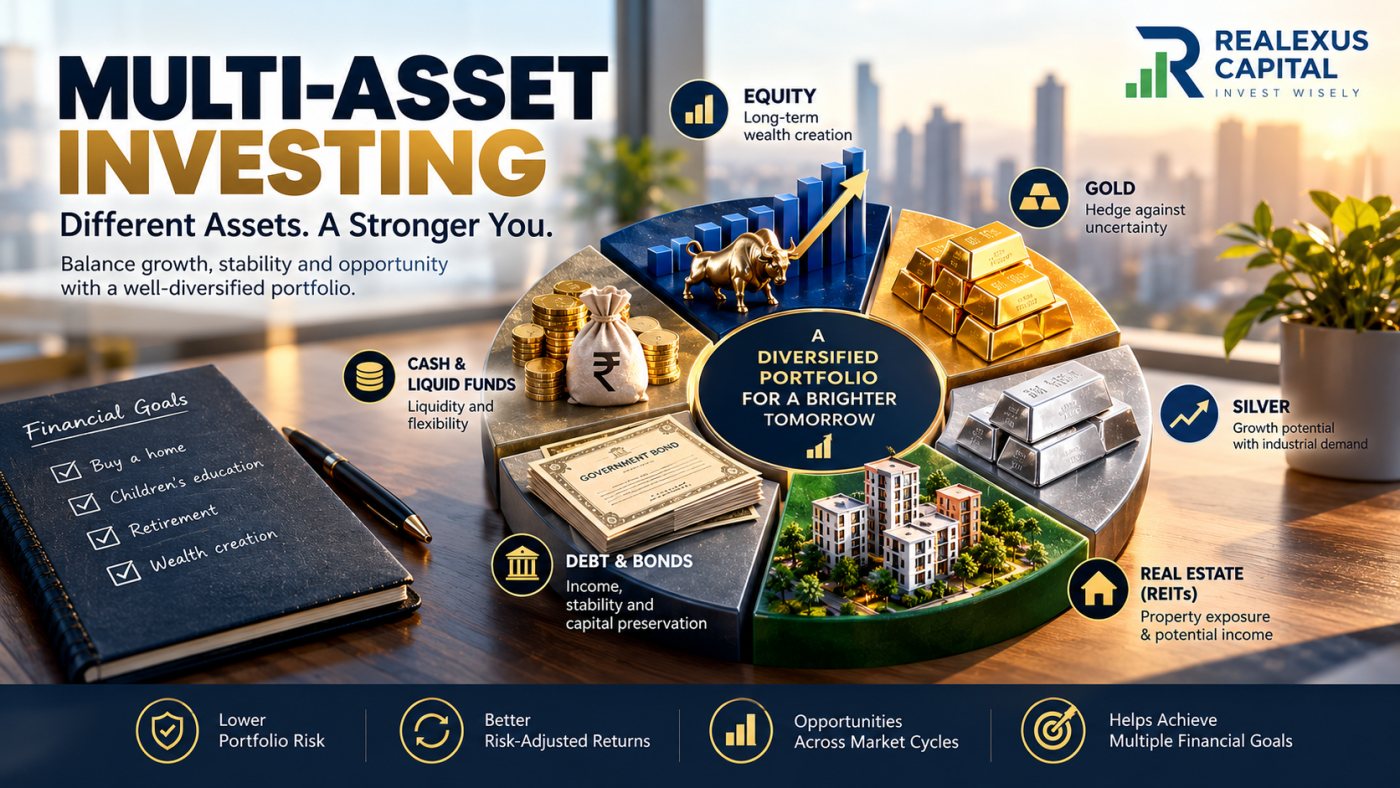
How combining equities, gold, silver, bonds and other investments can help build a more resilient portfolio.
What happens when equity markets fall, gold corrects, interest rates rise and global uncertainty increases?
Most investors start worrying about which asset will recover first.
But experienced investors ask a different question:
“Is my portfolio structured to survive different market conditions?”
That is where multi-asset investing becomes important.
The objective is not to predict the best-performing asset every year. It is to build a portfolio in which different investments play different roles, helping investors manage volatility while pursuing long-term wealth creation.
1. What is multi-asset investing?
Multi-asset investing means spreading investments across different asset classes rather than depending entirely on equities, mutual funds, real estate or gold.
Each asset class behaves differently depending on economic growth, inflation, interest rates, liquidity and geopolitical developments.
| Asset class | Role in a portfolio |
| Equity | Long-term capital appreciation |
| Gold | Diversification and potential protection during uncertainty |
| Silver | Precious-metal and industrial-demand exposure |
| Debt and bonds | Income and relative stability |
| REITs / real estate | Property exposure and potential income |
| Cash / liquid funds | Liquidity and flexibility |
The real advantage comes from combining assets whose performance drivers are not identical. However, correlations can change, and diversification cannot eliminate losses.
2. How multi-asset investing benefits investors
Benefit 1: Reduces dependence on equity markets
A portfolio invested entirely in stocks is exposed to equity-market volatility. Adding debt, gold and other suitable assets can help reduce concentration in one market.
Benefit 2: Creates opportunities across economic cycles
During strong economic expansion, equities may perform well. During uncertainty, gold may attract demand. Higher interest rates can create opportunities in newly issued fixed-income securities, although existing bond prices may fall.
Benefit 3: Improves portfolio discipline
Instead of constantly shifting between popular investments, investors can maintain strategic allocations and rebalance periodically.
Benefit 4: Helps manage drawdowns
A diversified portfolio may experience smaller fluctuations than a concentrated equity portfolio, depending on the assets selected and their correlations. It does not guarantee capital protection.
Benefit 5: Supports different financial goals
Equities may suit long-term wealth creation, while high-quality short-duration debt and liquid assets may be more appropriate for nearer-term requirements.
3. How should investors allocate their money?
There is no single ideal allocation for everyone. Age, financial responsibilities, risk appetite, investment horizon and liquidity needs should determine the mix.
For illustration, consider a balanced multi-asset portfolio:
Example for education only. Actual allocations should be based on an investor's circumstances.
For an investment corpus of ₹10 lakh, investors can compare three illustrative approaches:
| Asset class | Conservative | Balanced | Growth |
| Equity | 25% | 50% | 70% |
| Debt / bonds | 50% | 25% | 15% |
| Gold | 15% | 15% | 10% |
| Silver | 0% | 5% | 0% |
| Cash / liquid | 10% | 5% | 5% |
| Total | 100% | 100% | 100% |
These are simplified models, not personalized investment recommendations. Even conservative portfolios carry risks, including inflation, credit and interest-rate risks.
4. The real power of rebalancing
Imagine an investor starts with:
- 60% equity
- 25% debt
- 15% gold
After a strong equity rally, equity exposure increases to 70%.
Without rebalancing, the portfolio becomes riskier than originally intended.
A disciplined investor may reduce excess equity exposure or direct new investments toward underweight asset classes to restore the intended balance.
Rebalancing can help control risk and encourage systematic profit-taking, but taxes and transaction costs must also be considered.
5. How to start multi-asset investing in India
Investors can build their own diversified portfolio through equity mutual funds, ETFs, direct equities, debt funds, bonds, gold ETFs and other suitable instruments.
Alternatively, multi-asset mutual funds provide exposure to multiple asset classes within a single professionally managed scheme. Investors should examine the fund's actual allocation, costs, risks and tax treatment rather than assuming every multi-asset fund has the same strategy.
The most important steps are to identify financial goals, determine risk tolerance, select suitable assets, avoid unnecessary overlap and review allocations periodically.
6. The biggest mistake: Chasing last year's winner
When gold performs strongly, investors rush toward gold.
When small-cap stocks rally, portfolios become concentrated in small caps.
When silver rises sharply, investors suddenly want large exposure to silver.
This behaviour often results in buying after substantial price appreciation and selling after a correction.
Multi-asset investing replaces performance chasing with portfolio discipline.
A successful investment strategy is not necessarily about owning the asset that delivers the highest return in one year. It is about building a portfolio capable of supporting financial goals across many years.
7. The Realexus Capital perspective
At Realexus Capital Advisors, we believe portfolio construction should begin with understanding an investor's objectives rather than identifying the next trending stock.
A well-structured investment portfolio should answer four important questions:
- How much downside risk can the investor tolerate?
- Is the portfolio overly dependent on a single asset class or sector?
- Does the asset allocation match the investor's financial goals?
- When should the portfolio be reviewed and rebalanced?
Our investment philosophy:
“Wealth is not created by predicting every market move. It is built through intelligent allocation, risk management and long-term discipline.”